On 15 September 2026, the UK launched its latest Anti-Money Laundering (AML) and Asset Recovery Strategy 2026-2029. The publication aims to set the direction for the country’s AML infrastructure over the next 3 years. It emphasizes the need for smarter compliance controls amid evolving threats.
What is the Anti-Money Laundering and Asset Recovery Strategy 2026–2029?
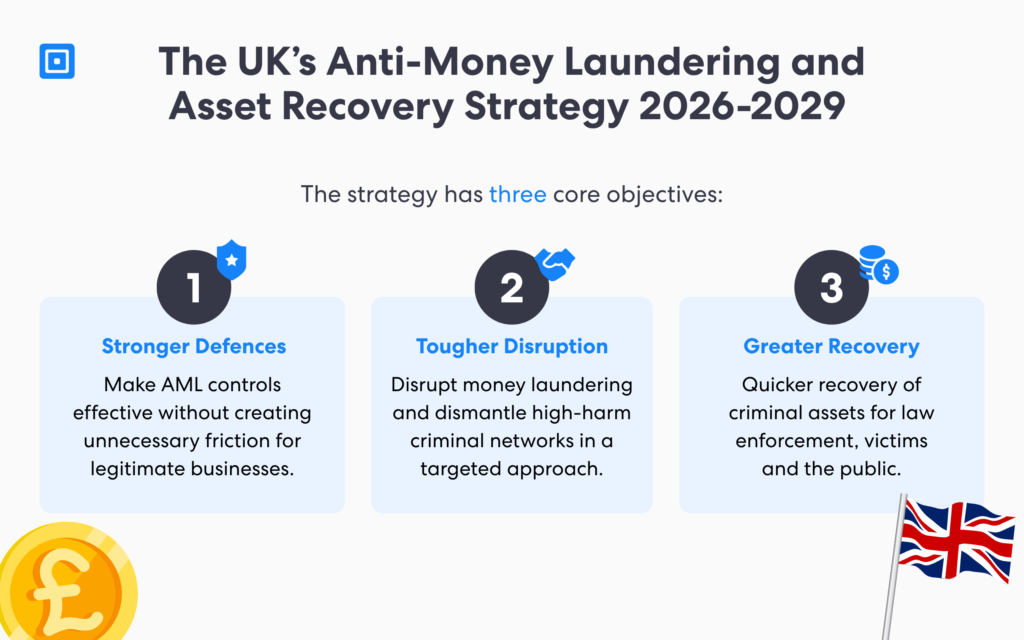
The Home Office and HM Treasury developed the UK’s AML and Asset Recovery Strategy to intensify the country’s response to financial crime. The strategy sets out a three-year roadmap to achieve three main objectives. Namely, to strengthen the UK’s AML defenses, disrupt high-risk money laundering networks, and recover criminal assets.
Financial crime is a corrosive threat that harms our communities and economy.
The program is backed by £520 million from the Economic Crime Levy, a further £30m from the high streets package announced at Budget 2025, and more than 500 new officers. Sal Melki, the Deputy Director at the National Crime Agency (NCA), emphasizes the need for this scale. She notes, “Financial crime is a corrosive threat that harms our communities and economy. It undercuts legitimate business, deprives our public services and furthers the interests of nations hostile to the UK and our way of life.”
Delivery will be structured via three pillars:
- Empower: Covers the people, technology, and legal powers needed to act on that intelligence.
- Target: Focus resources on the highest-risk activity rather than low-value compliance work.
- Integrate: Connect intelligence and organizations for a unified approach.
Why Did The UK Publish a New AML Strategy?
The new strategy aims to combine stronger enforcement with more proportionate regulation. The 2025 National Risk Assessment still classifies the UK as a country with high money-laundering risk. While the government reports improving outcomes, it argues that criminal threats continue to evolve.
During 2025/26, authorities disrupted more than 3,158 illicit finance systems, and recovered over £345.3 million in assets while returning £26.1 million to victims. Moreover, criminal cash-intensive businesses have resulted in over £10.7 million in suspected criminal funds seized or restrained.
Moving forward, the government aims to harmonize intelligence systems and sharing, as well as speed up asset-recovery processes. The government expects businesses to shift away from low-value activity. They must strengthen unified AML and fraud prevention controls.
What do Compliance Officers Need to Know Right Now?
It’s important to note that the strategy is not a new AML regulation in itself. Businesses can expect more consultations, guidance, and legislation in the upcoming months. Existing obligations under the Money Laundering Regulations 2017 (MLR2017), as amended in 2026, the Proceeds of Crime Act 2002 (POCA), and sector-specific rules still remain.
However, there are several developments businesses should be tracking:
1. Re-check your high-risk-country logic
From 30 June 2026, Enhanced Due Diligence (EDD) obligations have been narrowed to the Financial Action Task Force (FATF) “High-Risk Jurisdictions subject to a Call for Action” list. This means jurisdictions under the previous “Increased Monitoring” list will not mandate EDD immediately. However, this does not mean a grey-listed jurisdiction is automatically low-risk.
What this means: Firms should amend country controls to differentiate between a regulatory trigger and a firm-specific risk trigger. AML teams must consider geographic risk, FATF evaluations, and their own customer and transaction risk assessment, with clear rules and an auditable reason for EDD escalation.
2. Turn “risk-based” into something you can evidence
The strategy specifically calls out the need to focus on high-impact risks, without excessive compliance effort spent on low-risk customers or entities. Additionally, it encourages supervisors to discourage blanket or excessive controls and instead move to proportional measures.
What this means: An effective AML process should use the level of risk present to decide whether to route a customer to a particular journey. All escalation rules and compliance decisions must therefore trace back to the risk signal identified. This means more risk mapping and documentation on how the customer’s risk was determined, why a check is proportionate, and what decision followed.
3. Get ahead of AI governance
The Financial Conduct Authority (FCA) is due to publish its framework around good and poor practice for AI in 2026/27 and update its Financial Crime Guide with these examples. However, firms should not just wait for that guidance before establishing basic governance.
What this means: Mentioning that an AML provider “uses AI” will not translate to effective oversight. Where AI or machine learning is deployed in identity verification, fraud detection, and AML workflows, firms must understand and provide information on what data informs the system, how thresholds are controlled, where human intervention occurs, and whether decisions can be reconstructed.

Find out more AML news in ComplyCube’s Trust Edition newsletter. We explore the latest in developments across identity verification and AML globally.