Kurz gesagt: An effective know your customer checklist helps businesses operationalize KYC compliance. This guide provides a practical KYC documentation checklist, including a customer due diligence checklist to support risk-based verification, ongoing monitoring, and audit-ready KYC processes.
Why is an Audit-Ready Know Your Customer Checklist Vital?
A structured know your customer checklist gives businesses a clear understanding of what to do at each stage. It ensures that every element of an effective Know Your Customer (KYC) program is connected to strengthen financial crime prevention. This is particularly important as regulators look beyond policy and technology to assess compliance.
KYC non-compliance can lead to severe reputational damage, monetary losses, and erode customer trust.
In August 2026, regulators fined UBS Financial Services $125 million for failures in its Customer Due Diligence (CDD) processes. This included weak oversight of high-risk clients linked to Russia and Latin America. Just two months later, Bank of America faced a $1.2 billion fine for Anti-Money Laundering (AML) violations, including gaps in its risk assessments.
For compliance teams, this guide will cover the key components of a practical KYC documentation checklist to support regulatory requirements, operational efficiency, and customer experience.
Define Ownership for Effective Know Your Customer Checklist
To start, the most critical component of a KYC documentation checklist is implementing clear responsibility. Internal control failures accounted for 54% of fines issued for KYC non-compliance between 2021 and 2025. This includes ambiguous handoffs and weak team expertise.
As such, it is important to implement strong internal governance:
- Clear lifecycle ownership structure: Document each team member’s responsibilities explicitly. Role-Based Access Controls (RBAC) ensure employees only access what they have permission for.
- Regulatory mapping: Map KYC processes to the relevant compliance framework. For example, KYC regulatory frameworks include the Financial Action Task Force (FATF) Recommendations and the Bank Secrecy Act. Additionally, regulatory changes require updating the KYC checklists.
- Governance documentation: The KYC policy must be approved and periodically reviewed by the relevant board committee. This includes any changes to escalation paths or suspicious cases.
Case Study: AMEX $350M Fine Over Historic AML Breaches
Weak Monitoring and Senior Management Oversight
Ergebnisse
- The bank faced a $350 million fine and a cease-and-desist order.
- The order required AMEX to address deficiencies in its compliance program promptly.
- AML compliance moves beyond documentation, requiring ongoing monitoring and testing.
1. Customer Identification Program Non-Negotiables
Der Kundenidentifikationsprogramm (CIP) is the first stage in a know your customer checklist under relevant US regulations. The process involves collecting customer data, such as name, address, and date of birth. CIP supports the broader AML program and helps prevent fraudulent activities or other potential risks in financial crime.
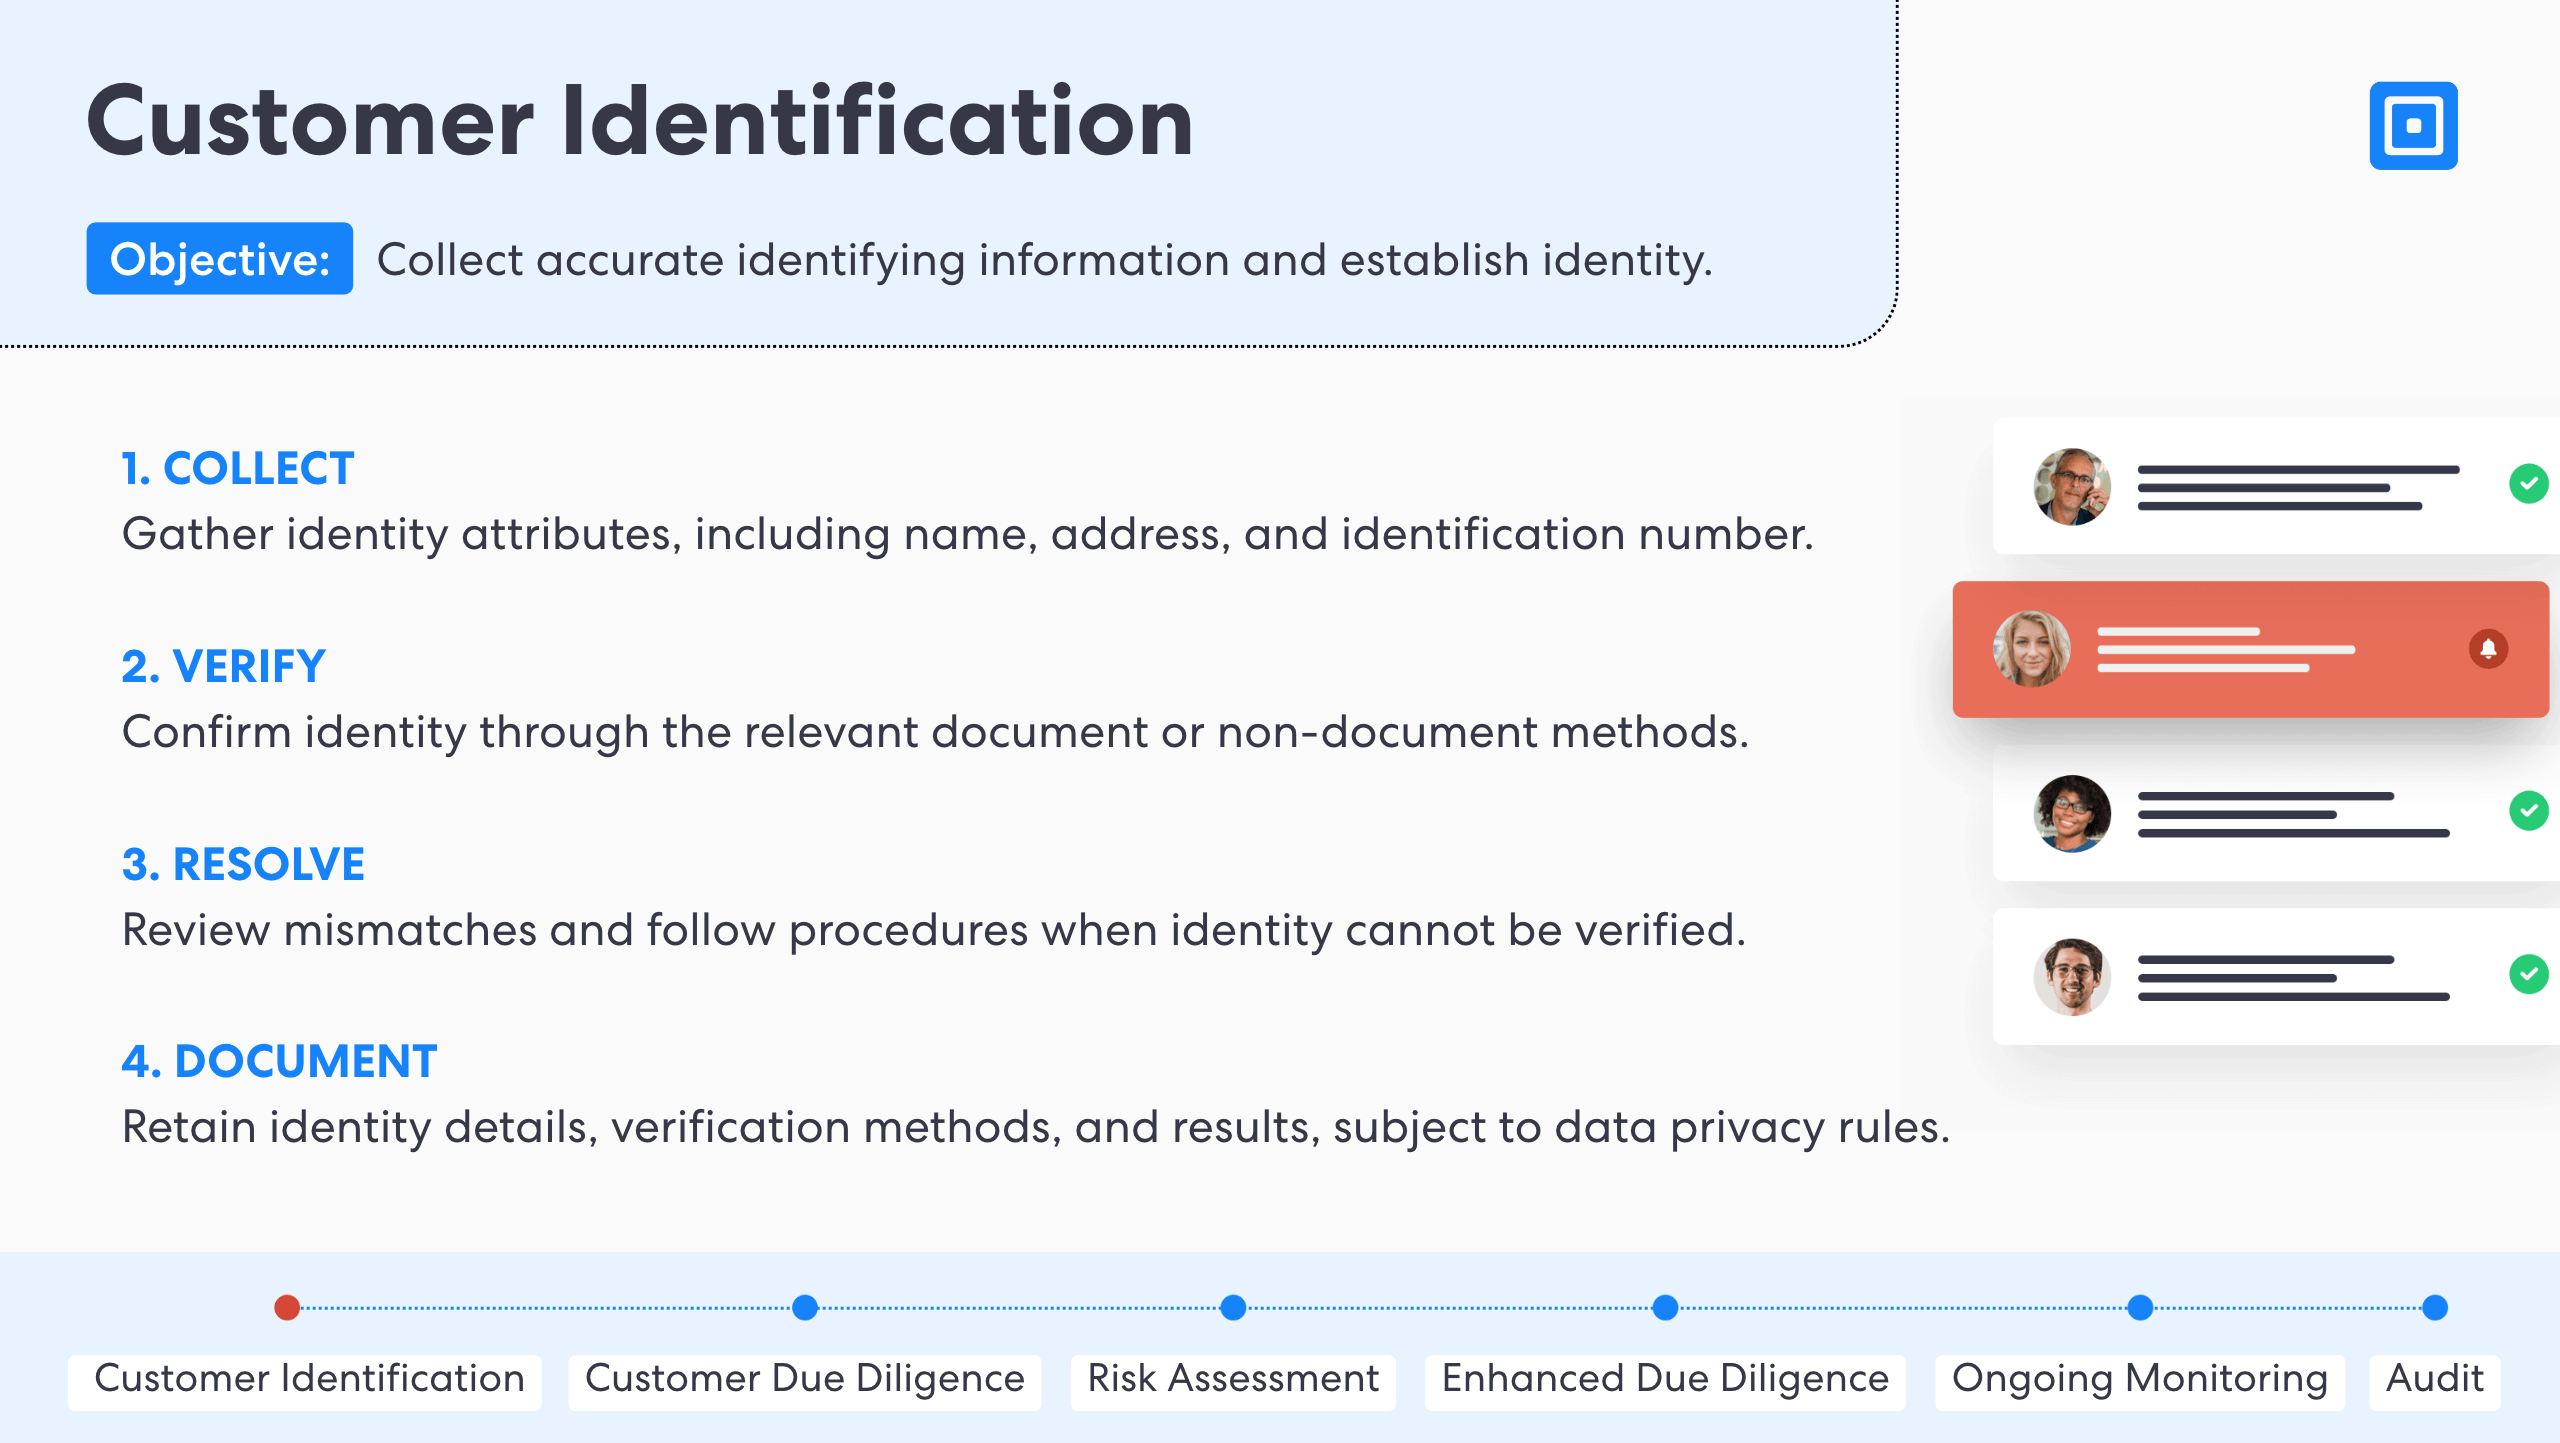
During CIP, businesses can perform identity verification, including document checks, biometrische Verifizierung, and database checks to capture identity information. Automated KYC tools support more accurate and secure data collection by reducing human error. Additionally, verification methods must be tailored to customer risks to enhance user experience while maintaining compliance.
2. Customer Due Diligence Checklist Requirements
Kunden-Due-Diligence turns static customer information into a fuller overview of an individual’s risk level. It goes beyond identification by helping financial institutions verify customer identity and understand beneficial ownership, the customer’s intended purpose, and the nature of the business relationship.
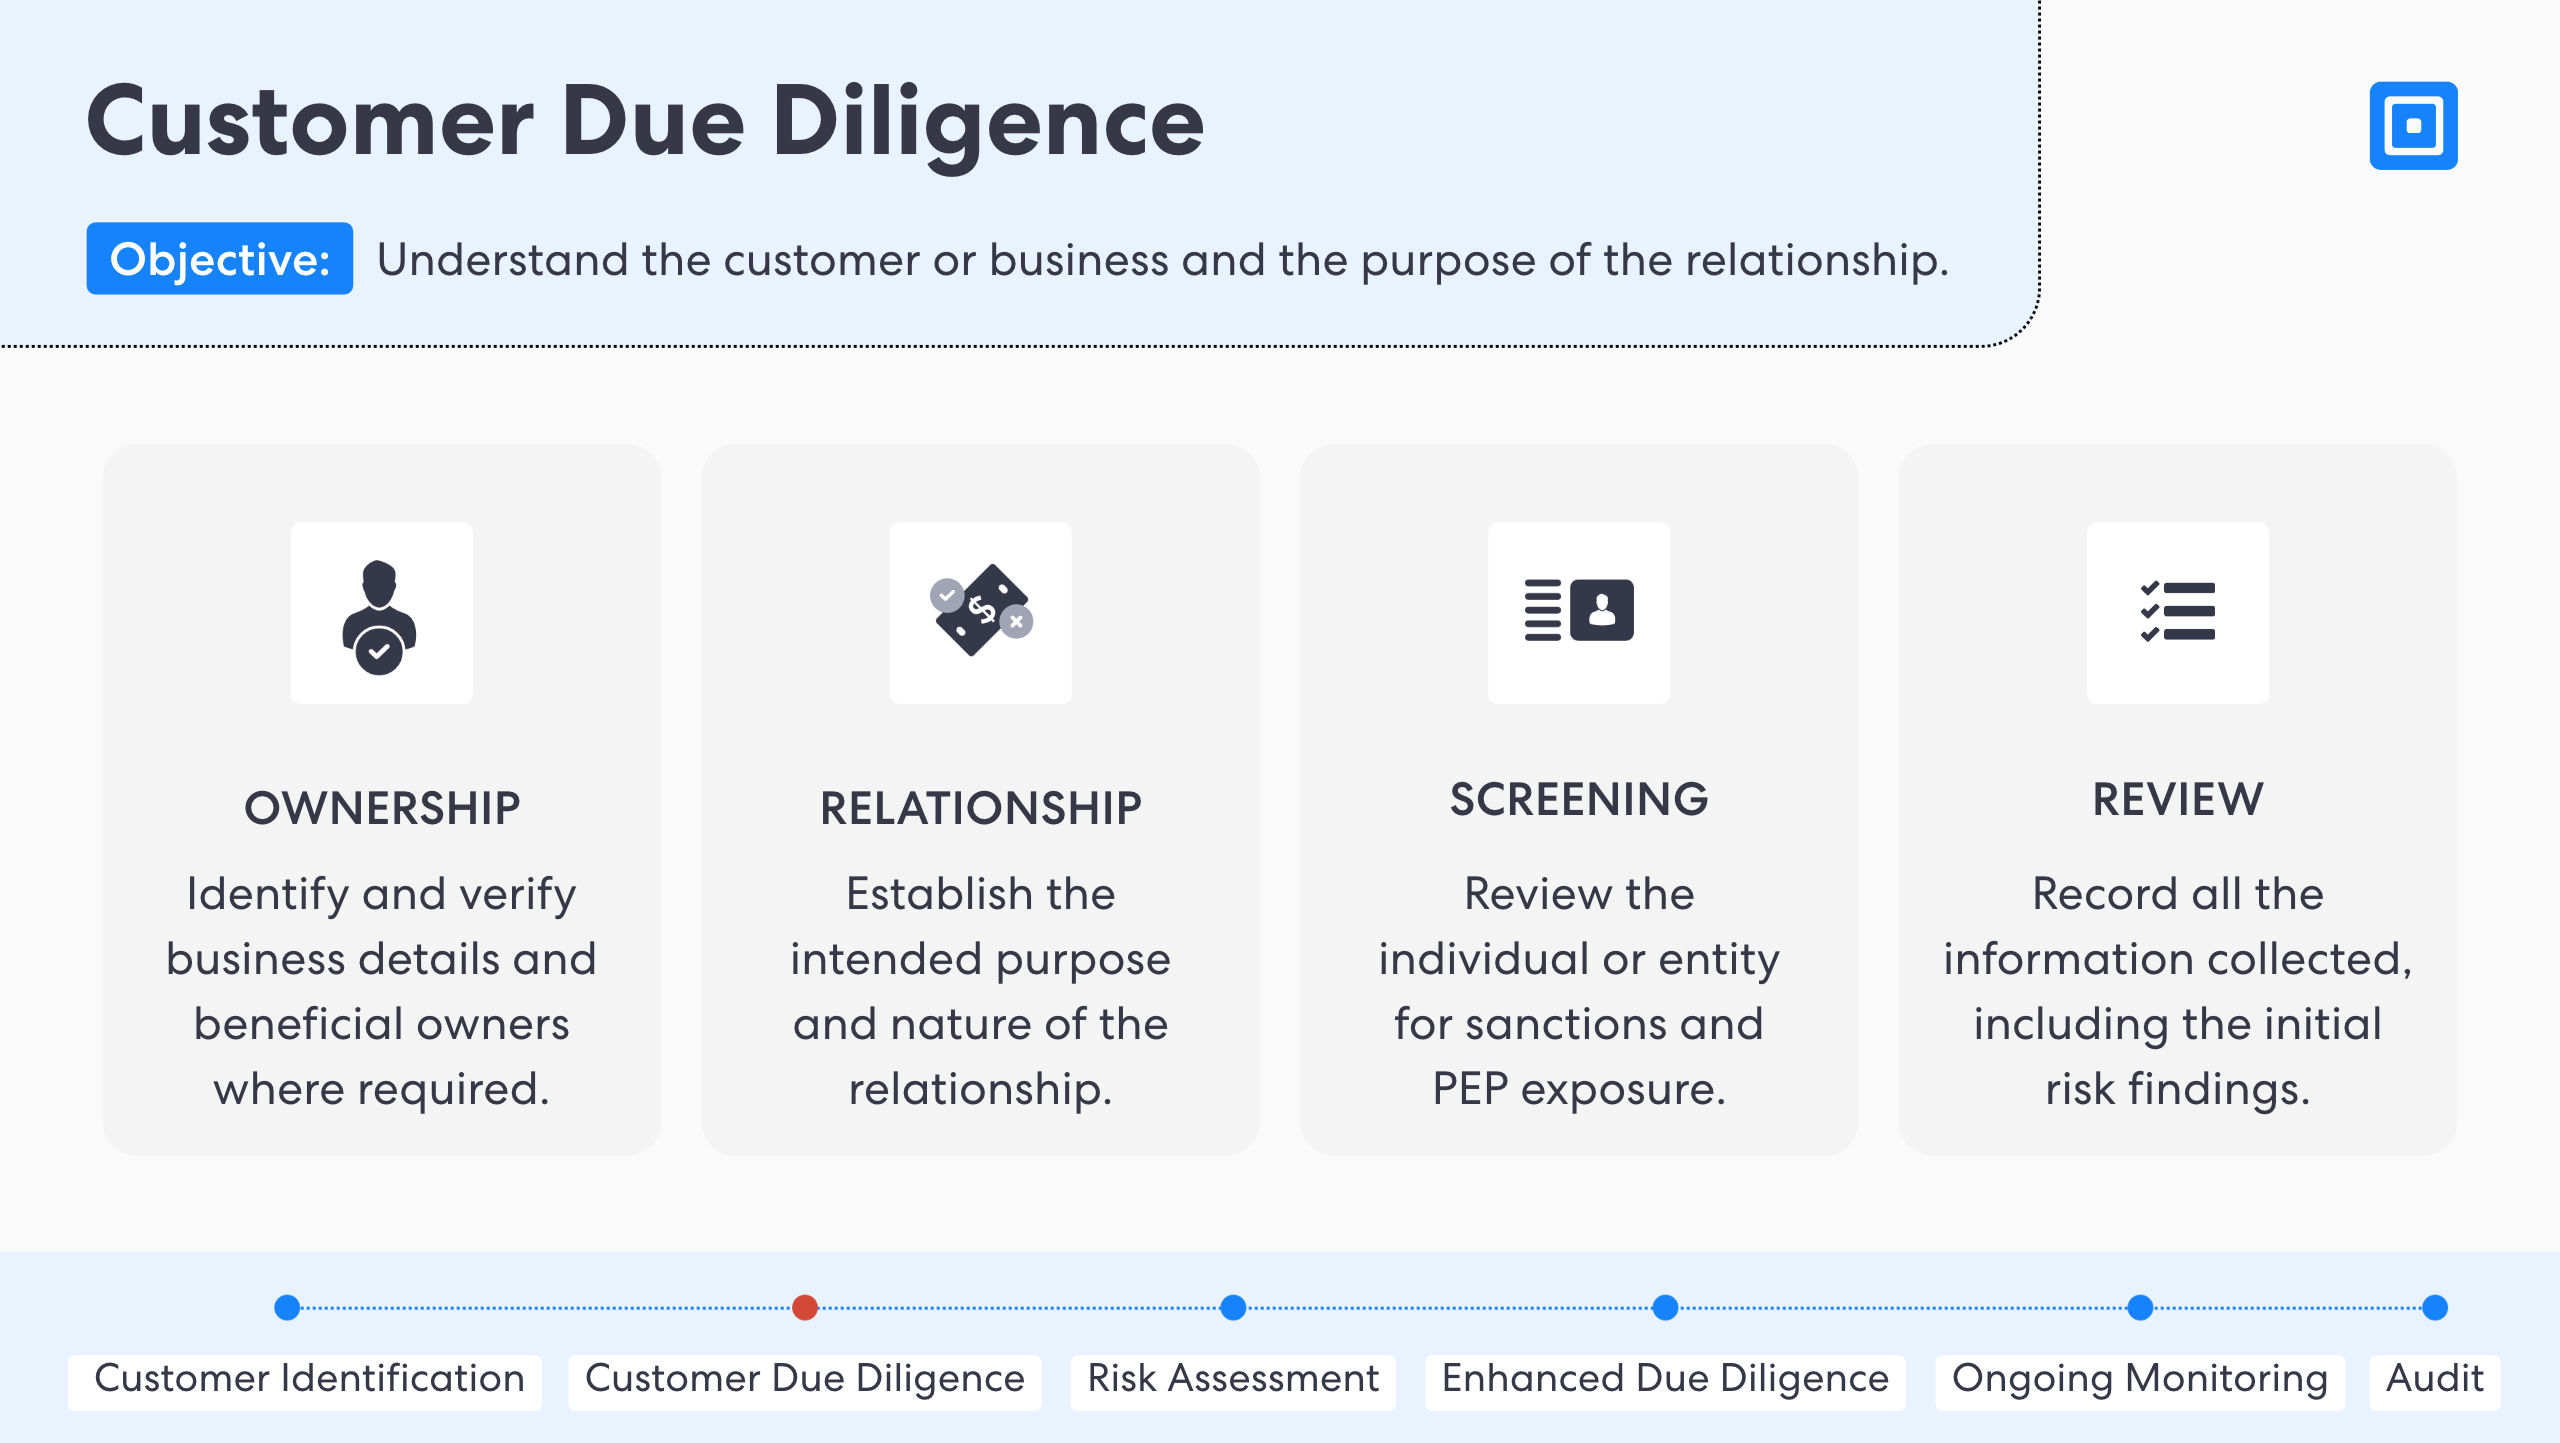
During CDD, a customer risk profile is produced, with typical risk ratings of low, medium, or high. This risk assessment determines whether further due diligence processes is needed. CDD is an ongoing process, and any material changes to customer information must be updated accordingly.
3. Risk Assessment as an Ongoing Process
Beyond assessing initial risk levels, businesses must maintain updated risk assessments in an ongoing manner. This ensures relevant data and risk factors continually reflect current risk exposure. For example, customer activity can influence risk exposure. This includes moving to a high-risk jurisdiction, unclear transaction purpose, and large cross-border payments.
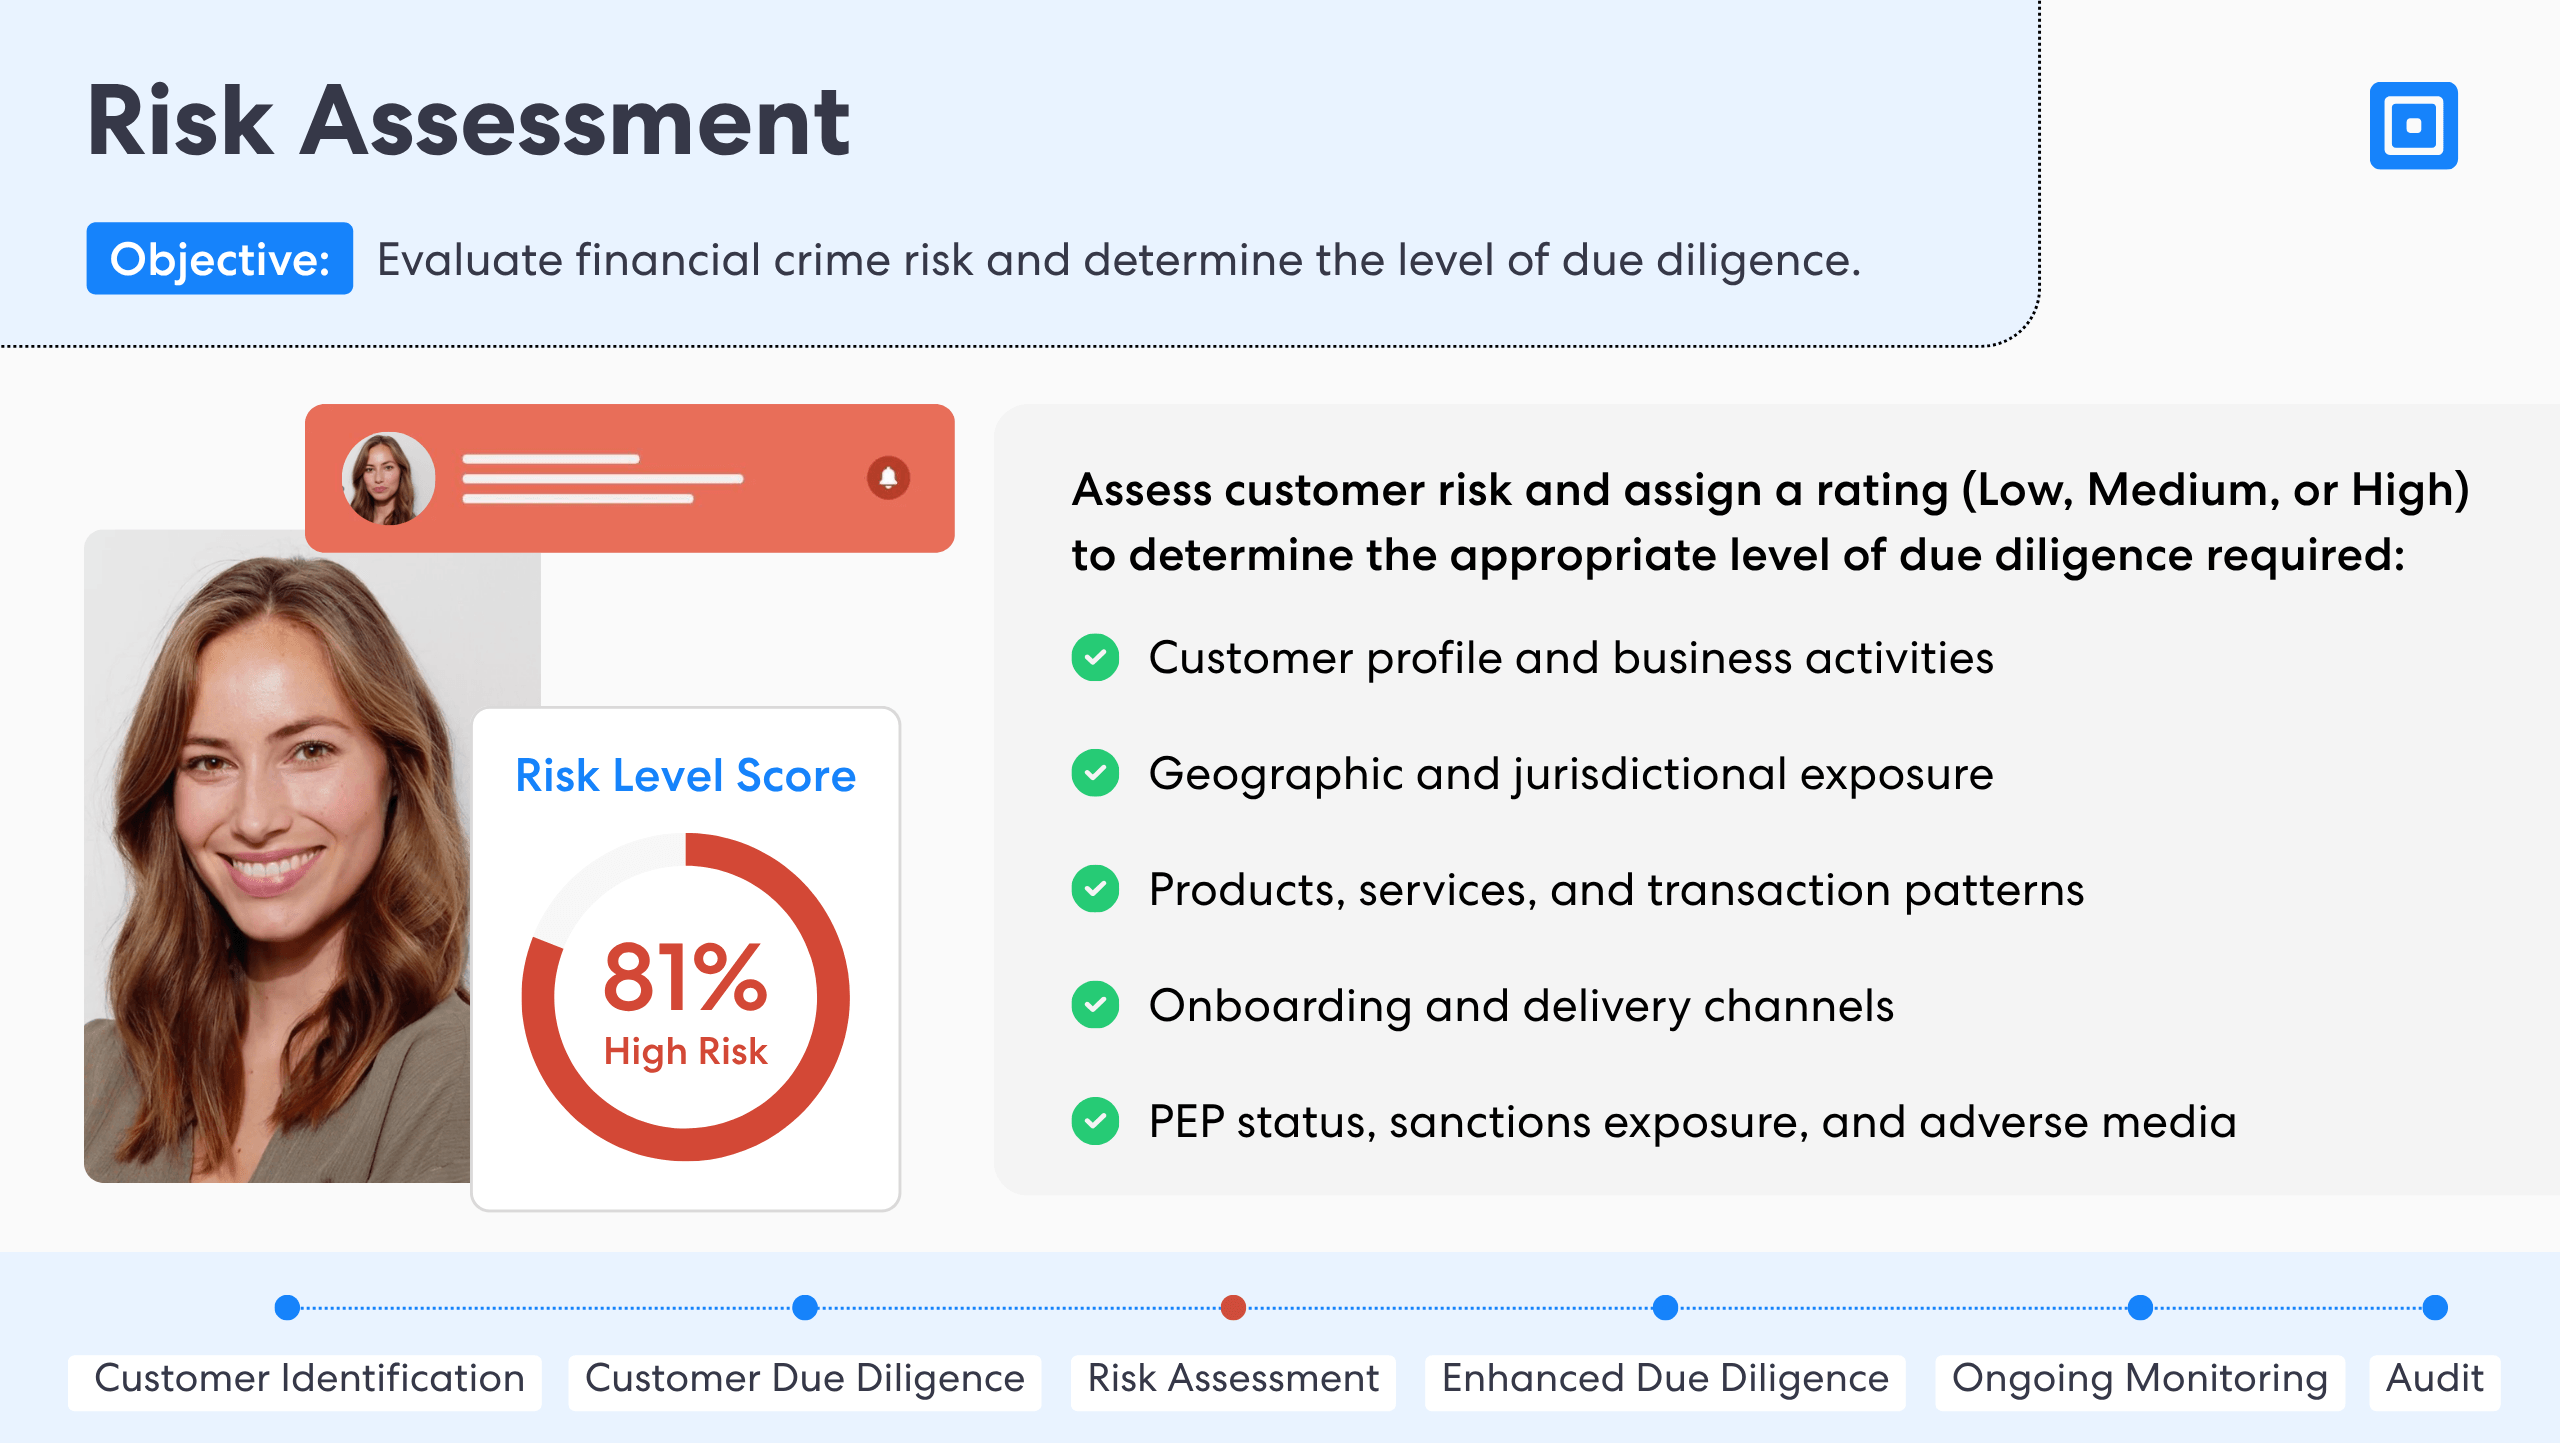
Businesses must incorporate any material changes to a customer’s or entity’s risk profile and related information into their risk assessment to support informed compliance decisions and help prevent money laundering and other financial crimes. You can learn more here: What is AML risk?
4. Enhanced Due Diligence for High-Risk Customers
For high-risk customers, businesses must apply Enhanced Due Diligence (EDD) measures. Common risk indicators include high-risk jurisdictions, Politisch exponierte Personen (PEPs), and complex business structures.
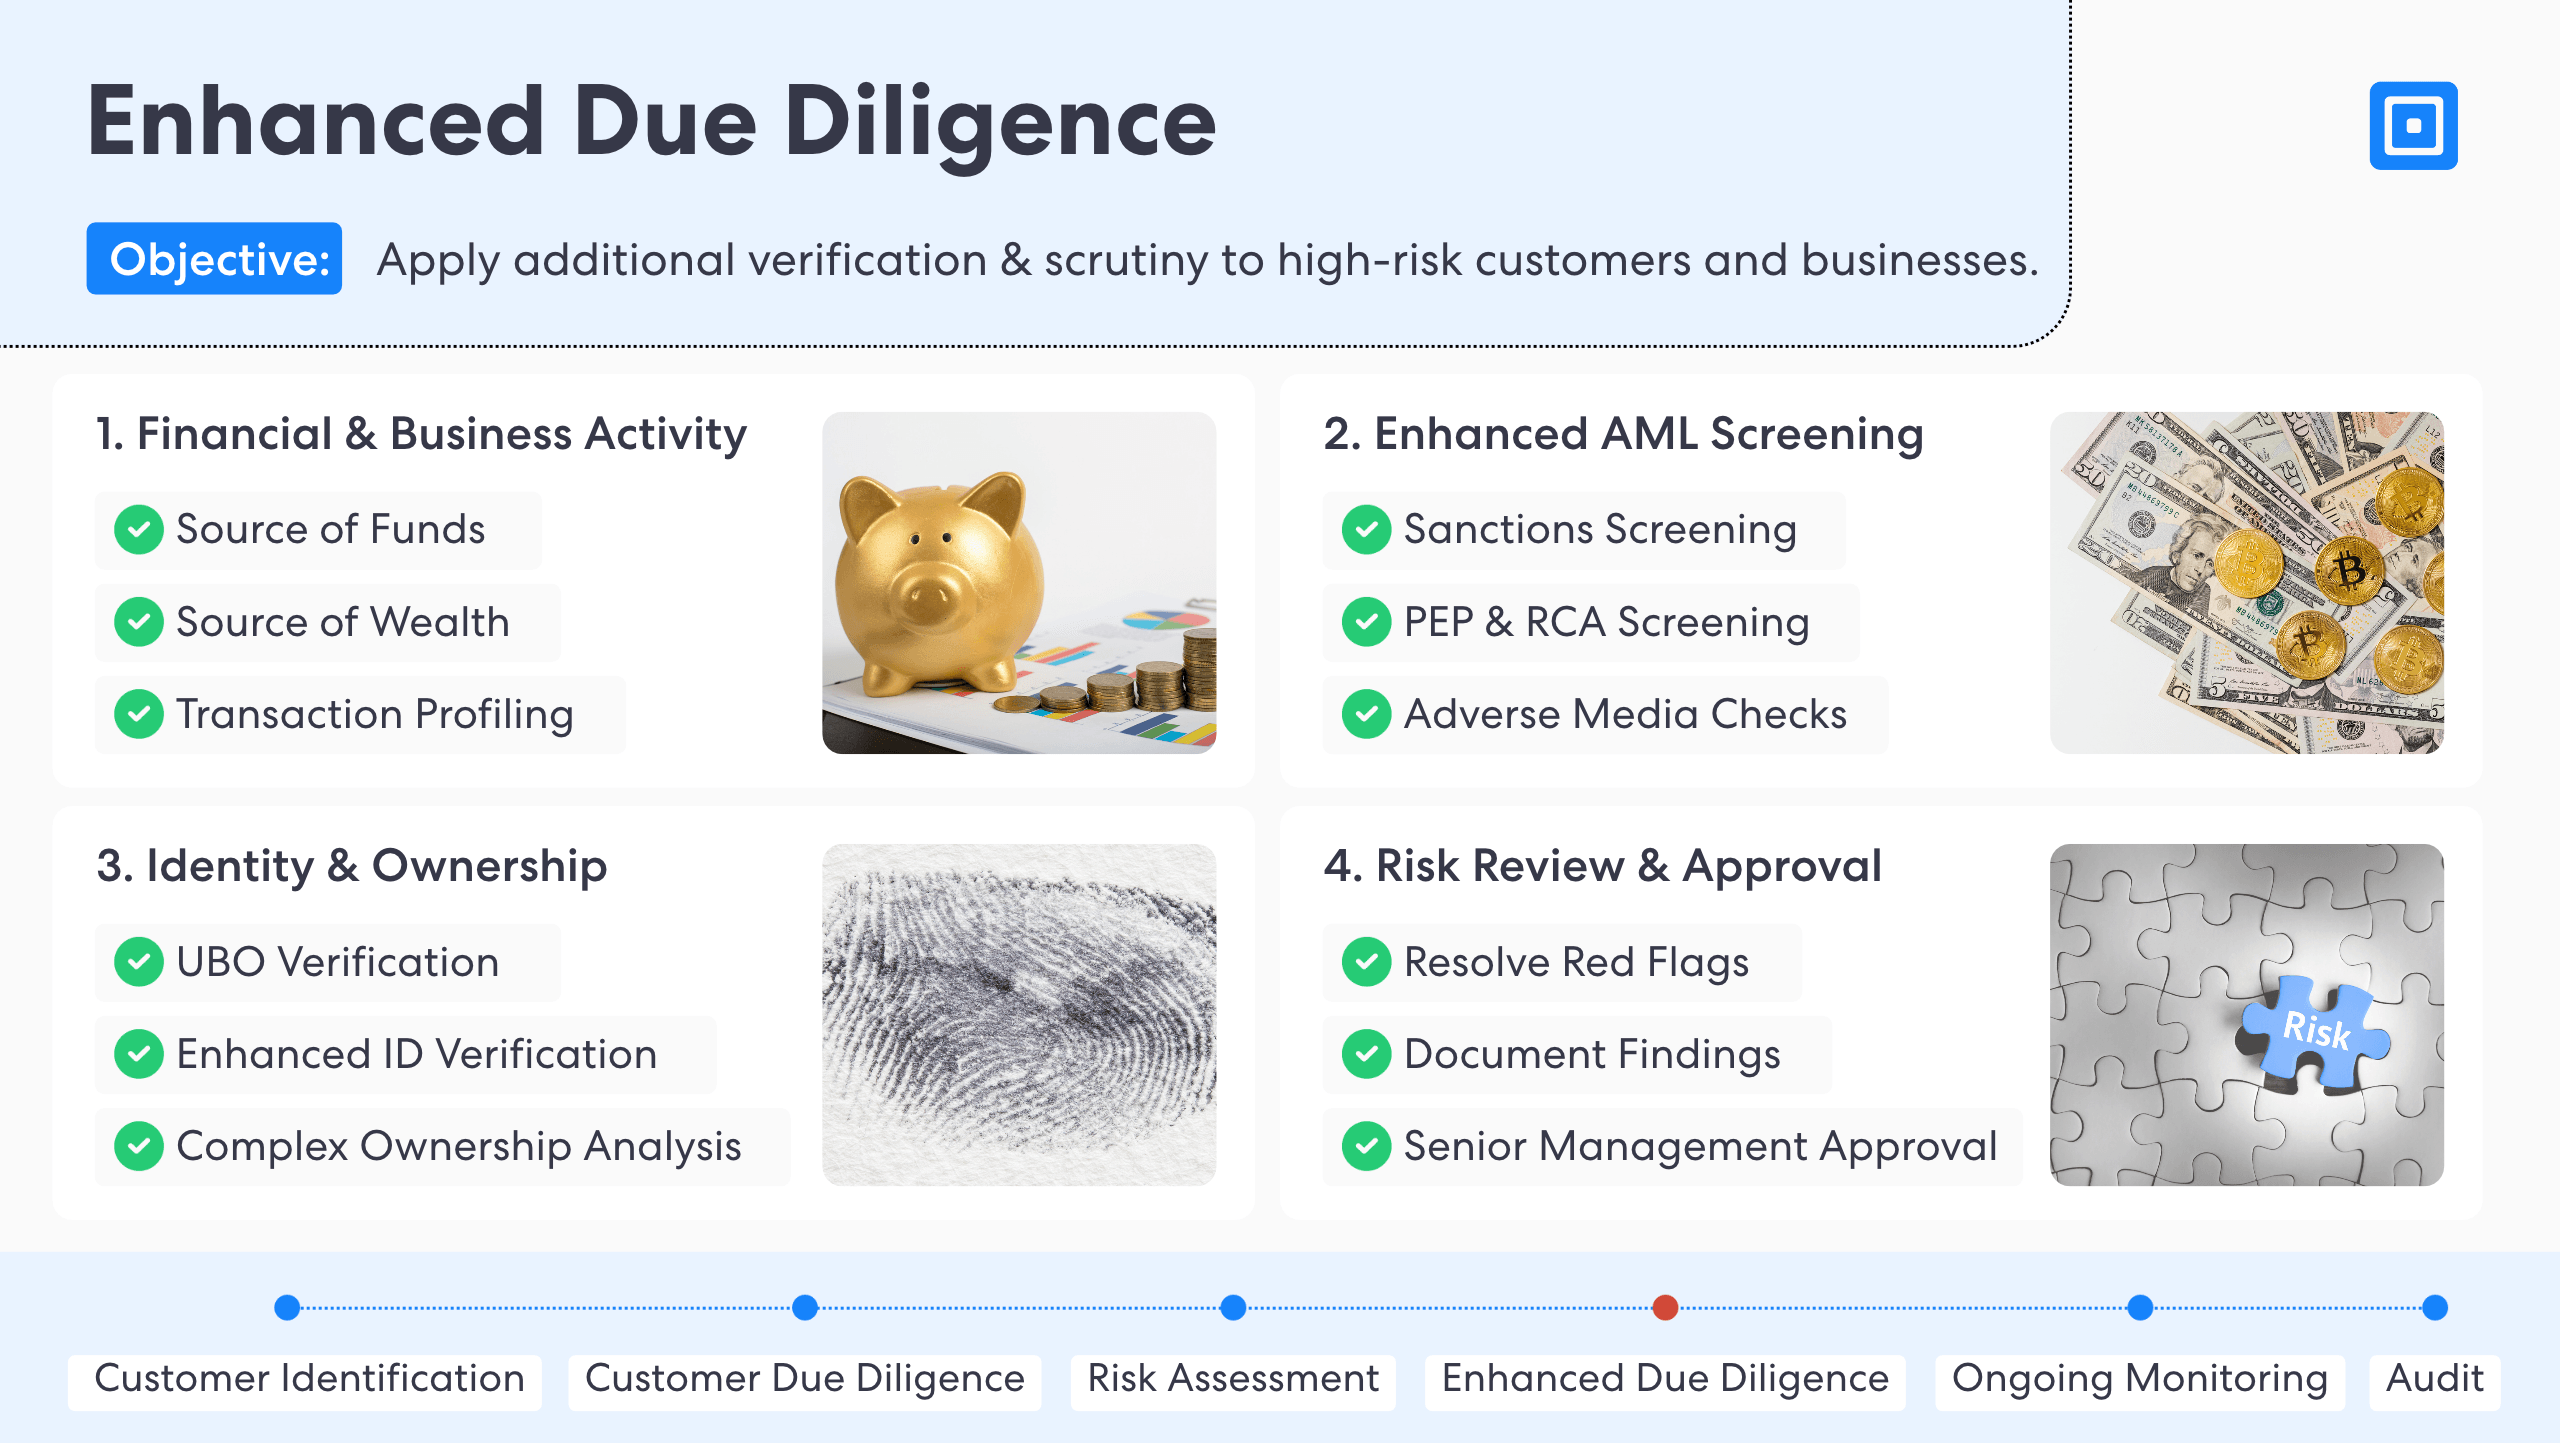
This vital process involves thoroughly analyzing a customer’s background, financial assets, and the purpose of transactions. Examples of checks performed at this stage include ultimate beneficial ownership verification, source of funds, and source of wealth checks. You can learn more here: Navigieren in der Welt der Enhanced Due Diligence.
During EDD, regulators will evaluate whether verification processes are proportionate to risk exposure. Thus, a risk-based approach is essential for effective due diligence measures. It streamlines onboarding for genuine users while applying step-up checks for higher-risk customers.
5. Ongoing Monitoring beyond Customer Onboarding
Beyond the onboarding process, ongoing monitoring is essential to identify suspicious behavior, changes in risk profiles, and maintain regulatory compliance. Typically, it includes screening for sanctions, PEPs, and adverse media. Sanctions and PEP screening are vital parts of KYC because they help mitigate risks related to terrorism financing and money laundering.
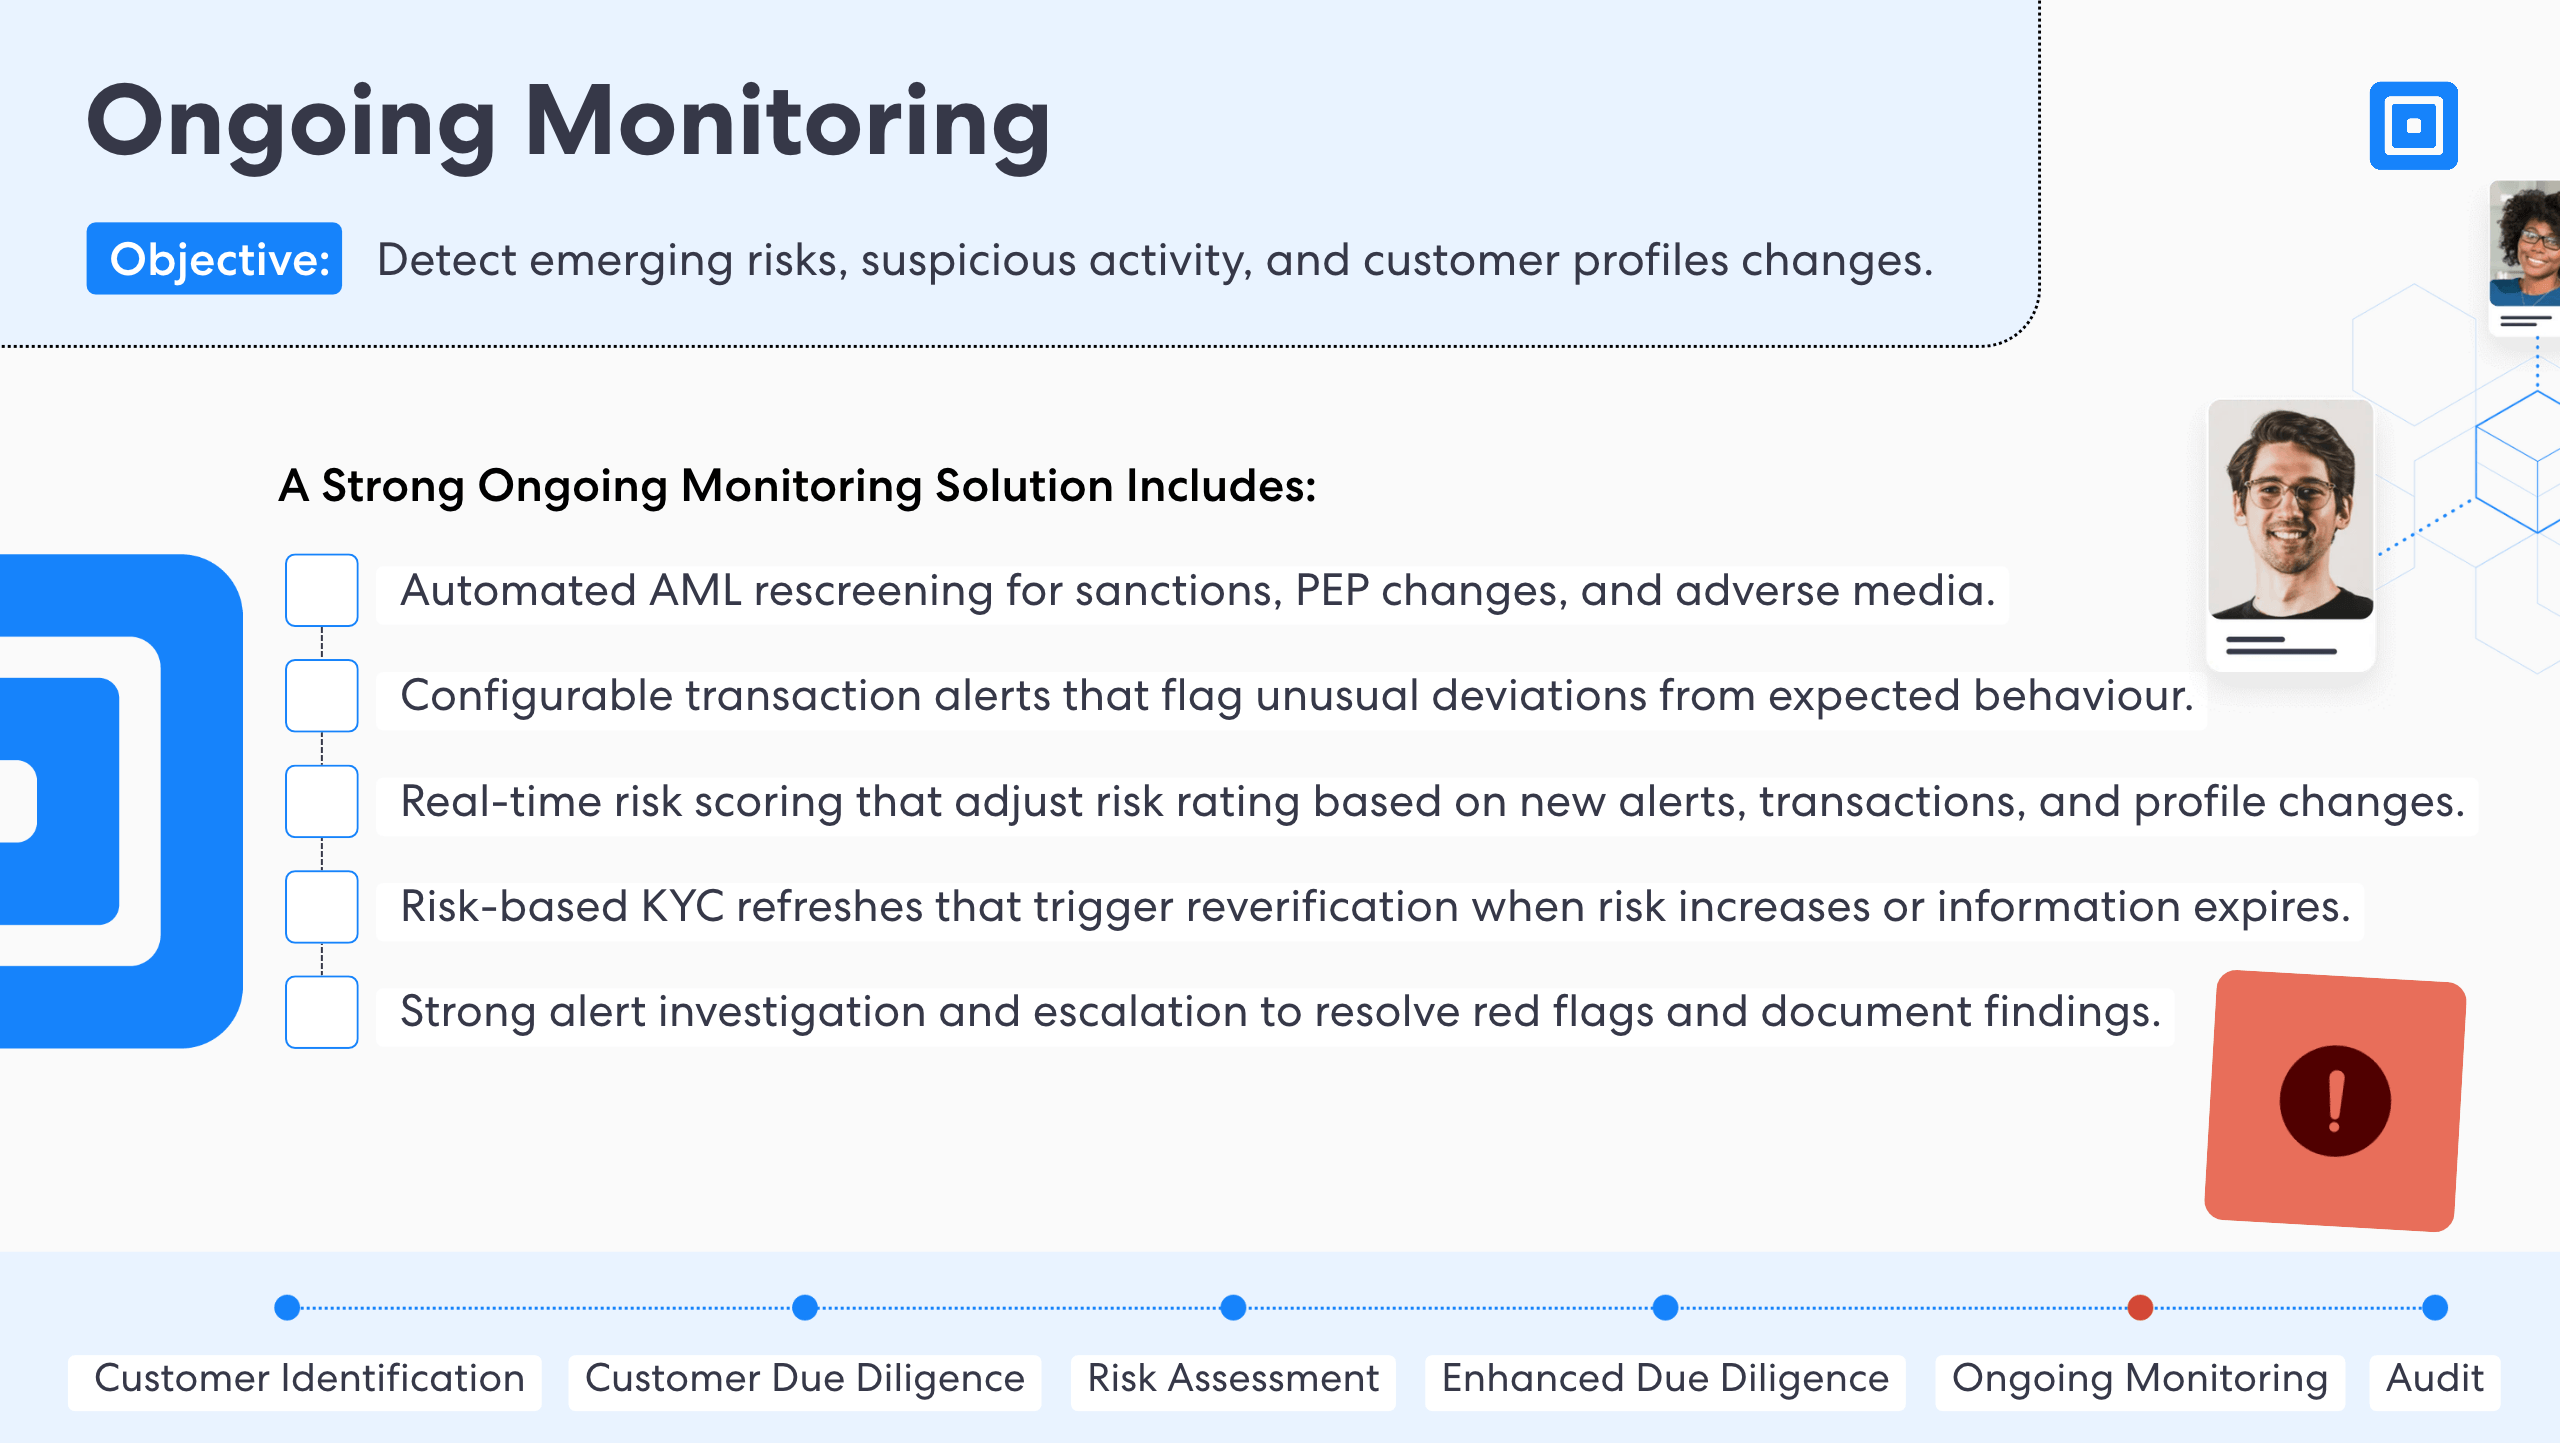
Moreover, transaction monitoring is crucial. It involves monitoring transaction patterns for spikes that deviate from expected behavior. Ongoing monitoring must connect to risk assessments to route customers to re-verification steps where required.
6. Dynamic and Audit-Ready Know Your Customer Checklist
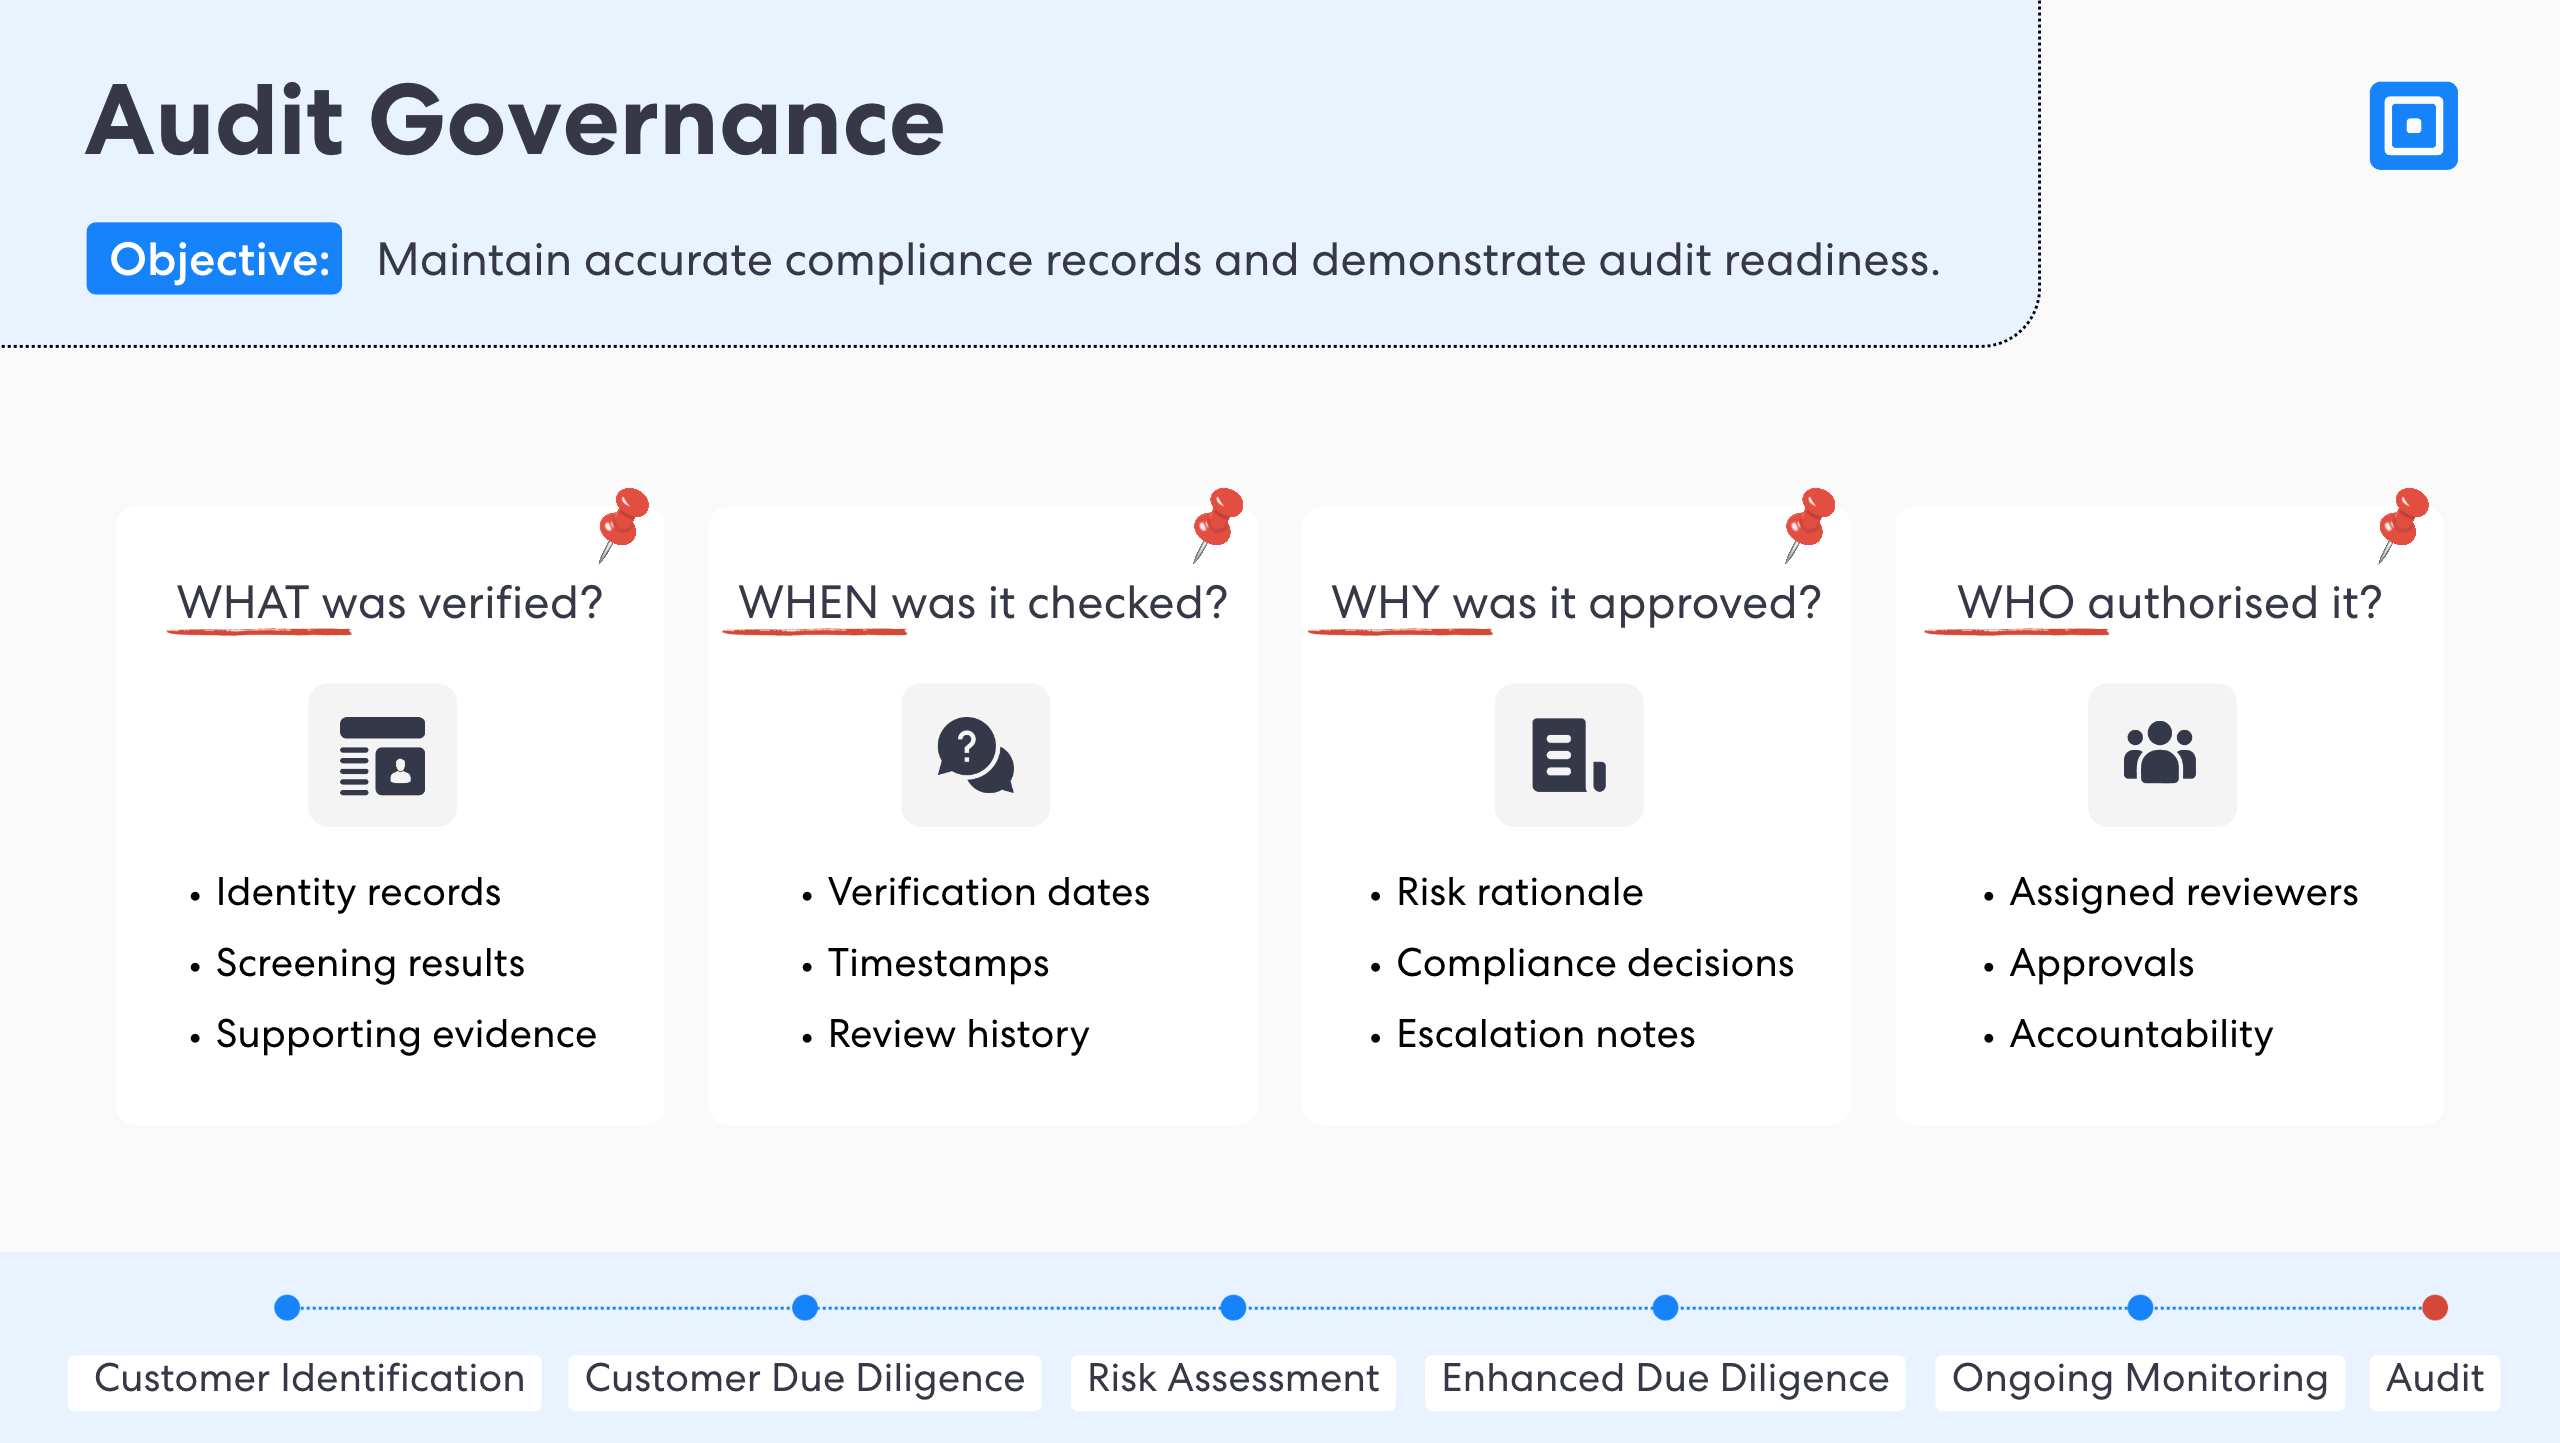
The risk landscape evolves rapidly. As such, a KYC documentation checklist must be reviewed periodically to reflect current risks and regulations. Additionally, an audit-ready know your customer checklist enables firms to show what they verified, when they performed checks, and the reasons behind their compliance decisions. Strong case management systems enable firms to document identity records, risk findings, and timestamped audit trails clearly for reporting.
Die wichtigsten Erkenntnisse
A practical know your customer checklist aligns with modern AML requirements.
An audit-ready KYC documentation checklist covers CIP, CDD, EDD, and ongoing monitoring.
KYC checklists must reflect regulatory and risk changes to ensure compliance.
Strong governance includes clear team ownership, audit trails, and defined escalation paths.
Laufende Überwachung helps detect risk changes by tracking customer relationship and activity.
Operationalize Know Your Customer Checklist
To summarize, a know your customer checklist helps businesses meet regulatory requirements beyond policy alone. It helps firms align with strong internal governance, a risk-based approach, and continuous monitoring. Automated, all-in-one KYC software allows regulated firms to centralize compliance requirements in one system.
ComplyCube’s award-winning fraud prevention platform combines strong KYC capabilities with flexible risk management controls. It supports full KYC compliance in over 250 territories, with powerful PAD Level 2 certified liveness biometric technology. Speak with a team member to learn more today.
Häufig gestellte Fragen
How to adapt global KYC checklist to multiple jurisdictions?
A global know your customer checklist does not require separate KYC programs per country. Instead, firms can create a universal program based on global KYC regulation standards such as the FATF Recommendations, then adapt it to local rules as needed.
Can we integrate AI into our KYC checklist?
Yes, AI can be integrated into a know your customer checklist. AI supports accurate, quicker, and cost-efficient KYC processes. However, clear AI model governance must be set to meet local rules. For example, document exactly how and when AI is used, and where human oversight is required.
How can we train staff to use KYC checklist correctly?
To train staff to use the KYC documentation checklist correctly, ensure training programs are practical and tailored to specific roles. Ensure that training reflects internal company policies and regulations. Practical sessions can include anonymized client cases to simulate real scenarios.
How to demonstrate a risk-based approach to regulators using KYC checklist?
To ensure know your customer checklist demonstrates an effective risk-based approach, ensure to document clear rationale and outcomes for distinct risk factors and levels. For example, a risk taxonomy and scoring model establishes how ratings and due diligence measures were derived.
Does ComplyCube support KYC due diligence?
ComplyCube offers end-to-end KYC lifecycle capabilities. It integrates identity verification, customer due diligence, ongoing anti-money laundering screening, and risk management in one platform. Regulated firms can verify identities, assess risk levels, and meet global KYC compliance.